EverythingYouNeedToKnowAboutTheHomeBuyingProcess

Dated: May 26 2020

Views: 629

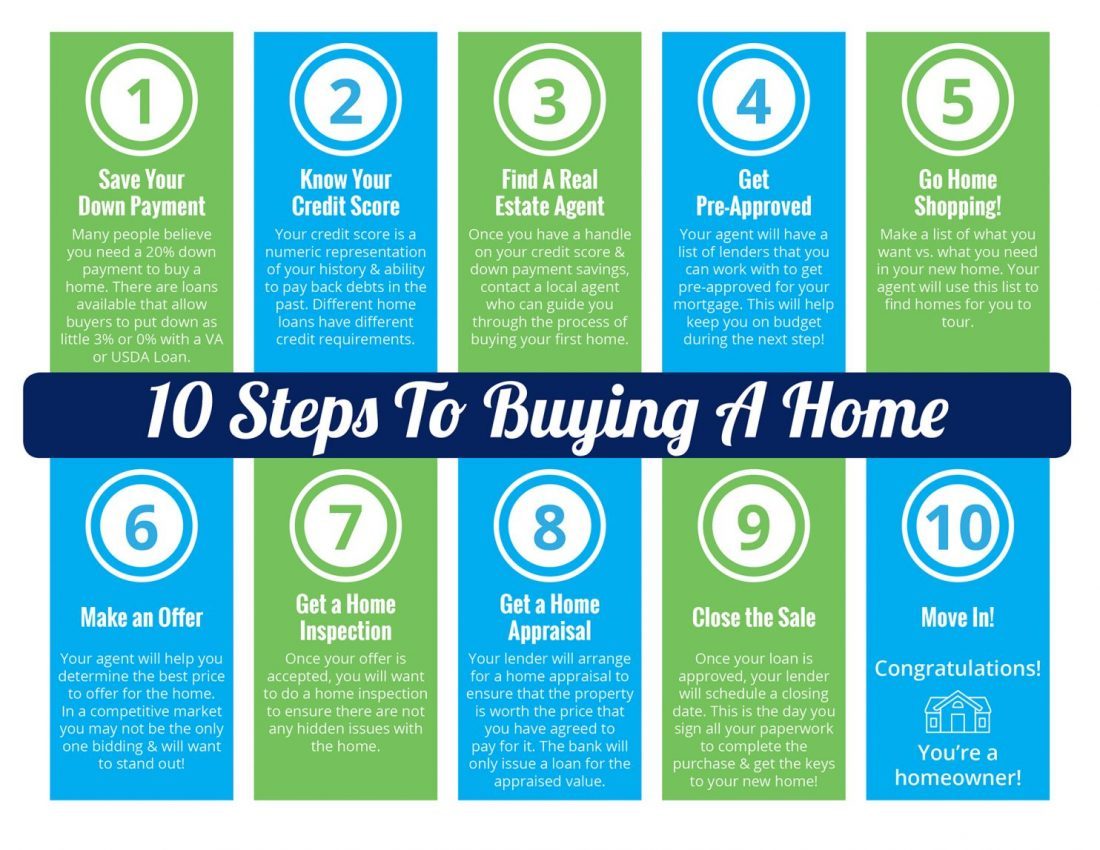
10 Steps To Buying A Home.

10 Steps To Buying A Home

If you're in the home buying market, knowing what to expect makes everything easier.

Here’s everything you need to know about how to buy a house in 10 steps:

    Step 1. Save Your Down Payment.

    Start saving for a down payment early.

    In addition to saving for a down payment, you’ll need to budget for the money required to close your mortgage, which can be significant. Closing costs generally run between 2% and 5% of your loan amount. You can shop around and compare prices for certain closing expenses, such as homeowners insurance, home inspections, and title searches. You can also defray costs by asking the seller to pay for a portion of your closing costs or negotiating your real estate agent's commission.

    It’s common to put 20% down, but many lenders now permit much less, and first-time homebuyer programs allow as little as 3% down. But putting down less than 20% may mean higher costs and paying for mortgage insurance, and even a small down payment can still be hefty. For example, a 5% down payment on a $200,000 home is $10,000.

    Some tips for saving for a down payment include setting aside tax refunds and work bonuses, setting up an automatic savings plan, and using an app to track your progress.

    Explore your down payment and mortgage options

    There are lots of mortgage options out there, each with its own combination of pros and cons. If you’re struggling to come up with a down payment, check out these loans:

    • Conventional mortgages They conform to standards set by the government-sponsored entities Fannie Mae and Freddie Mac and require as little as 3% down.

    • FHA loans Loans insured by the Federal Housing Administration permit down payments as low as 3.5%.

    • VA loans Loans guaranteed by the Department of Veterans Affairs sometimes require no down payment at all.

    Making a higher down payment will mean having a lower monthly mortgage payment.

    If you want the smallest mortgage payment possible, opt for a 30-year fixed mortgage. But if you can afford larger monthly payments, you can get a lower interest rate with a 20-year or 15-year fixed loan. Whether a 15-year or 30-year fixed mortgage is a better fit for you. Or you may prefer an adjustable-rate mortgage, which is riskier but guarantees a low-interest rate for the first few years of your mortgage.

    Research state and local assistance programs

    In addition to federal programs, many states offer assistance programs for first-time homebuyers with perks such as down payment assistance, closing cost assistance, tax credits, and discounted interest rates. Your county or municipality may also have first-time homebuyer programs.

    Determine how much home you can afford

    Before you start looking for your dream home, you need to know what’s actually within your price range to determine how much you can safely afford to spend.

    Step 2. Know Your Credit Score. 

    Check your credit and pause any new activity

    When applying for a mortgage loan, your credit will be one of the key factors in whether you’re approved, and it will help determine your interest rate and possibly the loan terms.

    So check your credit before you begin the homebuying process. Dispute any errors that could be dragging down your credit score and look for opportunities to improve your credit, such as making a dent in any outstanding debts.

    To keep your score from dipping after you apply for a mortgage, avoid opening any new credit accounts, like a credit card or auto loan, until your home loan closes.

    Compare mortgage rates

    Many home buyers get a rate quote from only one lender, but this often leaves money on the table. Comparing mortgage rates from at least three lenders can save you more than $3,500 over the first five years of your loan, according to the Consumer Financial Protection Bureau. Get at least three quotes and compare both rates and fees.

    As you’re comparing quotes, ask whether any of the lenders would allow you to buy discount points, which means you’d prepay interest upfront to secure a lower interest rate on your loan. How long you plan to stay in the home and whether you have money on-hand to purchase the points are two key factors in determining whether buying points makes sense.

    Step 3.Find A Real Estate Agent.

    Hire the right buyer's agent

    You’ll be working closely with your real estate agent, so it’s essential that you find someone you get along with well. The right buyer's agent should be highly skilled, motivated, and knowledgeable about the area.

    Step 4. Get Pre-Approval.

    Get a preapproval letter

    You can get pre-qualified for a mortgage, which simply gives you an estimate of how much a lender may be willing to lend based on your income and debts. But as you get closer to buying a home, it’s smart to get a preapproval, where the lender thoroughly examines your finances and confirms in writing how much it's willing to lend you, and under what terms. Having a preapproval letter in hand makes you look much more serious to a seller and can give you an upper hand over buyers who haven’t taken this step.

    Step 5. Go Home Shopping!

    House shopping tips

    Pick the right type of house and neighborhood

    You may assume you’ll buy a single-family home, and that could be ideal if you want a big yard or a lot of room. But if you’re willing to sacrifice space for less maintenance and extra amenities, and you don’t mind paying a homeowners association fee, a condo or townhouse could be a better fit.

    But even if the home is right, the neighborhood could be all wrong. So be sure to:

    • Research nearby schools, even if you don’t have kids, since they affect home value.

    • Look at local safety and crime statistics.

    • Map the nearest hospital, pharmacy, grocery store, and other amenities you’ll use.

    • Drive through the neighborhood on various days and at different times to check out traffic, noise, and activity levels.

      Make the most of open houses

      When you're touring homes during open houses, pay close attention to the home’s overall condition, and be aware of any smells, stains, or items in disrepair. Ask a lot of questions about the home, such as when it was built, when items were last replaced, and how old key systems like the air conditioning and the heating are.

      If other potential buyers are viewing the home at the same time as you, don’t hesitate to schedule a second or third visit to get a closer look and ask questions privately.

    Step 6. Make an Offer.

    Stick to your budget

    Look at properties that cost less than the amount you were approved for. Although you can technically afford your preapproval amount, it’s the ceiling — and it doesn’t account for other monthly expenses or problems like a broken dishwasher that arise during homeownership, especially right after you buy. Shopping with a firm budget in mind will also help when it comes time to make an offer.

    In a competitive real estate market with limited inventory, it’s likely you’ll bid on houses that get multiple offers. When you find a home you love, it’s tempting to make a high-priced offer that’s sure to win. But don’t let your emotions take over. Shopping below your preapproval amount creates some wiggle room for bidding. Stick to your budget to avoid a mortgage payment you can’t afford.

    Step 7 Get a Home Inspection.

    What is included in a home inspection?

    Home inspectors typically conduct a visual inspection of all parts of the property that are readily accessible. That leaves out anything that’s not easily viewed (or even visible), like some types of pest infestation, as well as any areas that are hard to safely reach (think wells and chimney interiors).

    Parts of the home that are commonly included in a home inspection:

    • Structural components (floors, walls, ceilings, stairs).
    • Exterior components (siding, attached decks, porches).
    • Roof.
    • Plumbing.
    • Heating and air conditioning.
    • Major appliances.
    • Ventilation.
    • Insulation.
    • Fireplaces and wood stoves.
    • Windows and doors.

    Not knowing the limits of a home inspection

    After your offer is accepted, you’ll pay for a home inspection to examine the property’s condition inside and out, but the results will only tell you so much.

    • Not all inspections test for things like radon, mold or pests, so be sure you know what's included.

    • Make sure the inspector can access every part of the home, such as the roof and any crawl spaces.

    • Attend the inspection and pay close attention.

    • Don’t be afraid to ask your inspector to take a look — or a closer look — at something. And ask questions. No inspector will answer the question, “Should I buy this house?” so you’ll have to make this decision after reviewing the reports and seeing what the seller is willing to fix.

      A standard home inspection provides you with a detailed report on the home you’re hoping to buy, but it doesn’t tell you everything.

      Depending on the age, location, and condition of the home you’re considering, you may need additional inspections. Radon testing, termite inspection, mold inspection, and foundation inspection are among the most common of these specialized types of home inspections.

    Step 8. Get a Home Appraisal.

    What is a Home Appraisal?

    A home appraisal provides a comprehensive look at what a piece of property is worth, and in turn, how much a lender is willing to loan you to buy that house. Home values in a specific geographical area are determined in part by the expert opinion of a professional appraiser, who visits and examines the size, condition, quality, and purpose of a home.

    Mortgage lenders require an appraisal on a house before they’ll provide a loan. A home appraisal will determine if a home’s value is overpriced, protecting a potential buyer from paying too much for a house. It also protects the bank from getting stuck with a property that’s worth less than the amount they’ve invested.

    While home appraisal regulations can vary state-to-state, essentially there are three aspects to the process:

    1. Inspection: A certified, state-licensed home appraiser will visit the property to determine the home’s value.

    2. Comparison to similar properties: The appraiser will research other homes that are in the same area and similar in makeup. He or she will compare recent home sales in the area to help determine a fair market value. If it’s new construction, the appraiser estimates the cost to replace the structure on the property if it were destroyed, and also takes into consideration land value and depreciation to determine the home’s value.

    3. Final appraisal report: Using the data from the inspection and comparables (comps), the appraiser will issue a final appraisal report.

    It’s important to remember that a home appraisal is not the same thing as a home inspection. If you’re buying a home, you’ll want to hire a licensed home inspector to highlight any potential problems with the house. Home appraisers will likely make note of any obvious issues, but they won’t test your HVAC system, inspect your chimney, or determine if your electric is up to code. That’s the job of the home inspector.

    What happens during a home appraisal?

    Properties that are just a couple of streets from one another can differ greatly in price. Accessibility to public transportation, the local schools, on what floor a condo is located, and what borders the property line are all factors that can make a big difference in the price of two seemingly similar homes.

    A common misunderstanding is that the appraisal amount is only for the house itself. In fact, the figure appraises the total value of the home and any other permanent structures, along with the land.

    Home appraisers look at a few key features when evaluating a property:

    Property size: An appraiser will consider the overall size of the plot of land, as well as the house, including the number of bedrooms and bathrooms. The more bedrooms and bathrooms, the more valued the house.

    The exterior: The appraiser will determine what materials comprise the exterior of the house (roof, siding, foundation) and evaluate their condition.

    The interior: Similar to the exterior, the appraiser will consider what interior materials were used and what condition they’re in. Damage or defects to the walls, windows, flooring and doors will be noted.

    Home improvements: Any improvements that were made under the current ownership can influence the appraised value of the home, such as a finished basement, a new patio, or an upgraded master bathroom.

    Extra features: Items such as a swimming pool, fireplace, or garage can increase the home’s value.

    While general tidiness of the home won’t help bring a higher appraisal amount, it's important the appraiser has a clear path to the property. Make certain the hedges are trimmed; gutters cleaned and remove any clutter that might impede an appraiser’s evaluation.

    Step 9. Close the Sale.

    It’s the home stretch! Getting familiar with the standard closing documents ahead of time can make the closing process less nerve-wracking. By this point, you should also know what you’ll owe when you sit down to sign the loan paperwork so you won’t be caught off guard by closing costs — some of which may be negotiable.

    • Find out what closing costs to expect.
    • Learn which closing documents you’ll encounter.
    • Negotiate for the seller (or even the lender) to pay some of the closing costs or other prepaid items, such as taxes.

    Step 10. Move-In!

    Moving is a lengthy process and involves several different steps.  Without a good organization, it can quickly become a daunting task, and things can get lost or forgotten in the mix.  In order to have a successful move that is hassle-free, it is helpful to set up a moving schedule.  This will help you stay on track and ensure that everything is done and ready to go come moving day.

    Sort and Purge

    Start Gathering Moving Supplies

    About 6 weeks prior to moving you will want to start gathering the necessary moving supplies. You will need to order and purchase supplies such as boxes, tape, bubble wrap, and packing paper.   You might also consider specialty boxes and containers for any valuable items. 

    Confirm Your Moving Company

    About 1 month before you move you should schedule your mover.  By this time, you should have a good idea of a closing date and this will give you ample time to secure a date.  Make sure the moving company gives you an estimate for moving costs and double-check to see that they are insured.

    Begin Packing

    As soon as your moving date is confirmed it is time to get packing.  You should begin with the items you use less frequently and save items such as kitchen dishes for a later time.  Take it one room at a time and take extra precautions when packing delicate or fragile items. 

    Sort and Label Your Boxes

    As you are packing it is important to label each box with the contents and the room it belongs to.  This will help the movers know where to place each box in your new home.  This will also make it easier for you to find items when you are unpacking.  Neatly stack and organize your boxes as you pack them so they will be easily accessible for your movers.  This will make things much more efficient on moving day.

    Pack Up Last-Minute Items

    One week prior to moving day it is time to go ahead and finish packing any remaining belongings including dishware.  Go ahead and trade your dishes and glasses for disposable cups and plates.  Pack a suitcase with necessary toiletry items that you will need up until the last day.  Do a final check around the house including the attic, garage, and storage shed to be sure you haven’t left anything behind.

    Move and Clean
    About 2 months prior to moving it is time to go through every room in your house and decide what you want to keep and what you can live without.  Set aside any items that you want to get rid of and decide if you will have a yard sale or you prefer to donate them.  Once you have purged all of your unwanted items, you should sort the items that you plan to keep.  Decide if you want to keep them out or if it is something that can go ahead and get packed.  This step will save you a great deal of time later down the road when it comes time to pack up your home.

    The final step in the process is moving day itself!  Once the movers have emptied your entire home, it is time to go behind them and give the house a good clean. This will ensure your house is ready for the new owners.  As boxes and furniture are being delivered to your new home, have the movers put items in the rooms where they belong.  This will make unpacking a much easier process.

    You may not be able to eliminate all of the stress associated with moving, but you can plan an organized move with the help of this step-by-step guide.  Following a schedule will help you to stay on track and make for a more enjoyable moving experience.
    We hope this information is helpful in understanding some of the important steps for buying a home. We are here to make this as smooth and efficient a process as possible.
    Selling or buying a home is a big decision and a long process.  It is important to have someone you can turn to and ask questions of.  I would like to earn the right to be that person.

    If you ever have any questions or want to know more, please feel free to reach out to me. It is a good idea to have someone on your side when purchasing a home. Here is my contact information, in case you misplaced it?

    Yamel Romano, Associate Broker
    RE/MAX Realty Advantage
    (210) 404-5590 Cell
    (210) 495-5252 Office
    Facebook:@YamelRomanoSanAntonioRealtor

    Blog author image

    Yamel Romano

    As a Real Estate agent, I’m professional, honest, and very dedicated to helping my clients find the home of their dreams. Whether you are buying or selling a home or just curious about the local....

    Latest Blog Posts

    BuyAHouseNowOrWaitForTheNewYearToCome

    BUY A HOUSE NOW OR WAIT FOR 2021 TO COME?Real estate investments are always a good idea, as property prices often tend to rise with time. If you have the money and a desire to invest, buying a house

    Read More

    WhatFeesCanYouExpectAtClosing

    What are closing costs?Closing costs are fees associated with your home purchase that are paid at the closing of a real estate transaction. Closing is the point in time when the title of the

    Read More

    WhyComparableSalesAreImportantWhenBuyingOrSellingAHome

    Why Comparable Sales Are Important When Buying or Selling a HomeBY ELIZABETH WEINTRAUB Updated April 01, 2019When it comes to the homebuying market, buyers and sellers both need

    Read More

    TypesOfMortgageLoansForHomebuyers

    Types of Mortgages: Which Is Right for You?A house is probably one of the biggest purchases you’ll ever make. And—despite what “normal” broke people might tell you&mdash

    Read More